Written by Peter Regalado, Operations Manager · Reviewed by Mason Pastorello, Managing Director · Last reviewed: July 2026
Your roof insurance deductible is the amount you pay out of pocket before your coverage kicks in on a claim. If your deductible is a set dollar amount, you pay that amount and the insurer covers the covered damage beyond it. If it's a percentage deductible, you pay a percentage of your home's insured value — which can be considerably more. Understanding your deductible is essential, because it directly determines whether a claim is worth filing and how much a roof replacement will actually cost you.
This article explains how roof deductibles work, the difference between flat and percentage deductibles, and an important Colorado-specific point about deductibles you need to know. It's general information, not legal or insurance advice.
What a deductible is and how it works
A deductible is your share of a claim. When you have covered damage, the insurer subtracts your deductible from what they pay, so the deductible is effectively your first-dollar responsibility on any claim. A higher deductible generally means a lower premium — you're taking on more of the risk yourself — and a lower deductible means a higher premium. On a roof claim, the deductible comes out of your settlement, which is why it matters so much for the math of whether to file.
Flat versus percentage deductibles
Deductibles come in two main forms, and the difference can be large.
- A flat (or fixed dollar) deductible is a set amount — you pay that specific figure regardless of the claim size. This is straightforward and common.
- A percentage deductible is calculated as a percentage of your home's insured value, not the claim amount. Some policies, particularly in areas prone to certain kinds of storms, apply percentage deductibles to wind or hail claims specifically. Because a percentage deductible is based on your dwelling coverage, it can translate to a much larger out-of-pocket number than a typical flat deductible, especially on a higher-value home.
It's important to check whether your policy has a separate wind or hail deductible, and whether it's a flat amount or a percentage — because that single detail can dramatically change what a roof claim costs you.
How your deductible affects whether to file a claim
Your deductible is often the deciding factor in whether filing a claim makes sense. If your covered damage is less than or close to your deductible, filing may not be worth it — you'd pay the deductible and receive little or nothing, and you'd have a claim on your record. If the covered damage substantially exceeds your deductible, a claim usually makes financial sense.
The Colorado point you must understand about deductibles
Here is a crucial Colorado-specific caution. In Colorado, offers by contractors to waive, absorb, cover, or pay your insurance deductible are a serious legal red flag. Colorado has law addressing roofing contracts and insurance, and it is generally not permissible for a contractor to entice you by promising to make your deductible disappear or to rebate it back to you.
Comparison of flat dollar and percentage roof insurance deductibles
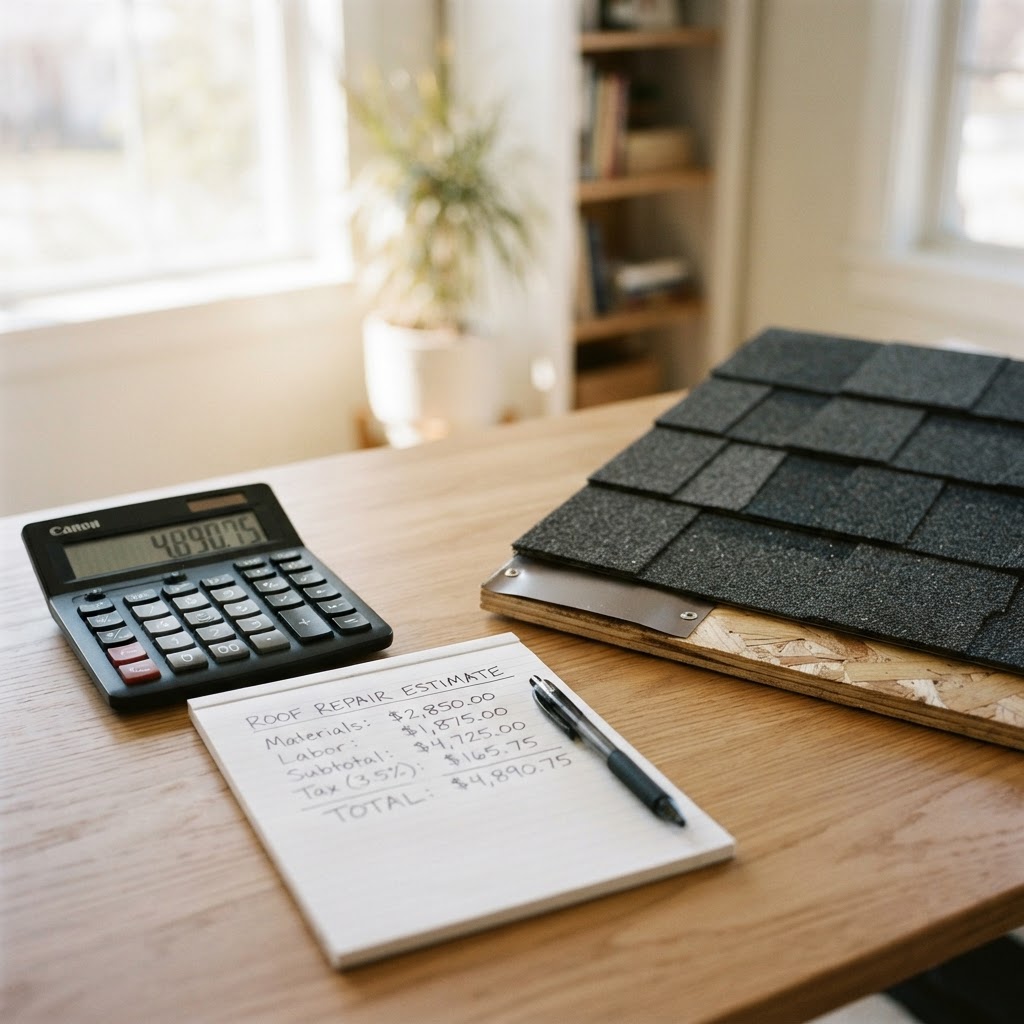
Illustration of how a deductible affects whether to file a roof claim.
Frequently Asked Questions
- Licensed & insured — documentation available on request
- Free, documented roof inspections
- Real emergency service available
- 5-year workmanship warranty (manufacturer warranties vary by product)
- 30 years of construction experience
- Serving Denver, Adams, Arapahoe, Douglas, Jefferson, and El Paso counties
Promise Keepers Restoration
9615 E. County Line Rd, Ste. B-477, Centennial, CO 80112
Hours: Mon–Sat 8:00 AM–5:00 PM